Build your dream home
Building a new home or renovating an existing property can be an exciting but daunting process. Our experienced team can guide you through the process and help you find the financing solution that fits your needs.
Expert construction loan guidance
A construction loan is a type of home loan designed for building a new home or major renovations, where funds are disbursed in stages aligned to construction progress rather than as a single lump sum. Obtaining the right construction loan for you to build a new home requires some expertise from your Mortgage Broker. We have extensive expertise in construction loans in New South Wales. We understand the intricacies involved in financing the construction of a new home or significant renovations. Use our loan repayment calculator to estimate your construction loan repayments once the build is complete.
A Residential Construction Loan is specifically designed to assist individuals in building their dream homes or undertaking substantial renovations on existing properties. Unlike traditional home loans, which are dispersed in a lump sum, construction loans are disbursed in stages to align with the progress of construction.
At Gateway Finance we recognise that each construction project and each borrower's financial situation is unique. Therefore, we offer a range of Residential Construction Loan options that can be tailored to meet the specific requirements of the project and the borrower's financial circumstances.
Loan Stages
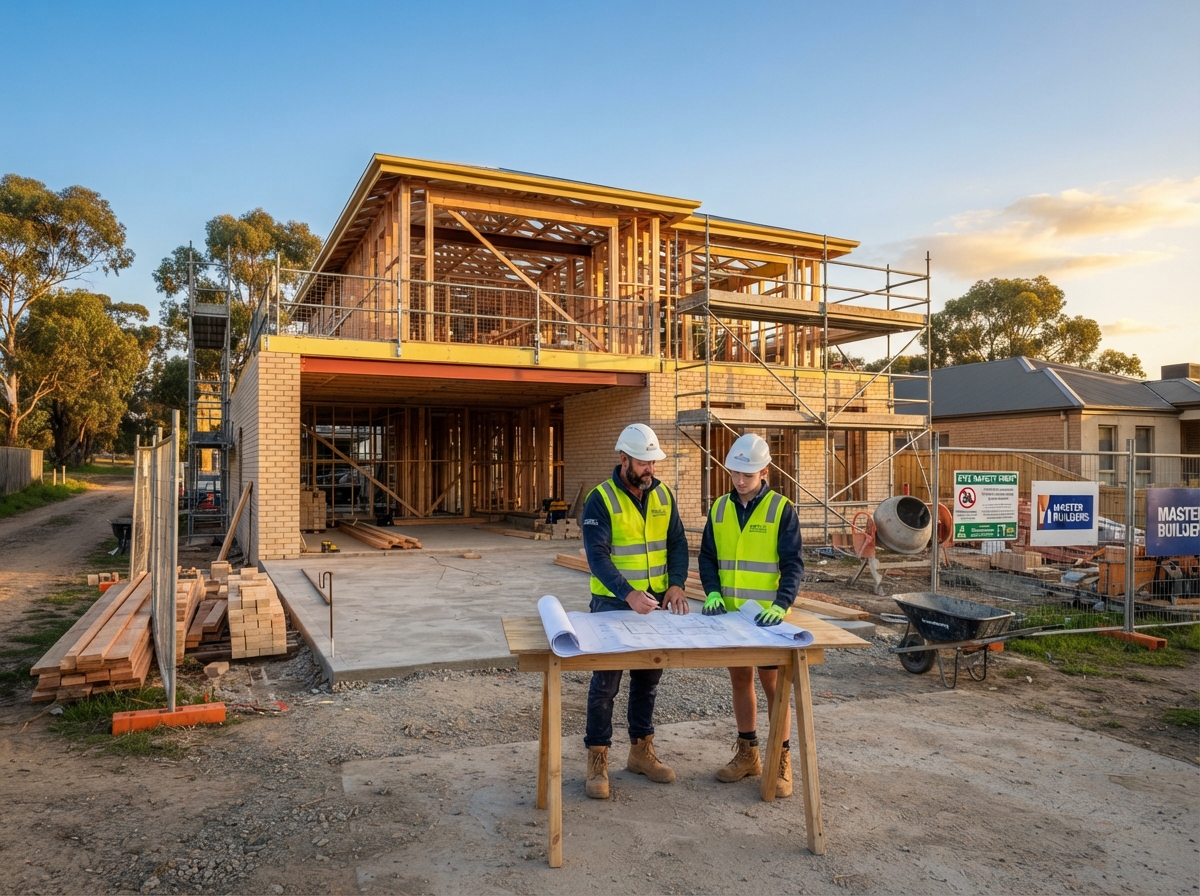
Unlike conventional home loans, construction loans are broken down into stages which correspond to certain stages in the construction process.
Deposit Stage
Initial deposit to secure the construction project.
Slab Stage
Funding for the concrete slab and initial construction work such as plumbing etc.
Frame Stage
Funds for erecting the structural framework for the property.
Lock Up Stage
Funding for enclosing the property, including walls, roof, and windows.
Fit Out Stage
Funds for interior fixtures and fittings.
Completion Stage
Final funds to complete the construction project.
How staged disbursement works
Throughout the construction period, the lender disburses funds to the builder in stages to cover the costs of materials and labour as construction progresses. This staged disbursement ensures that funds are used efficiently, and construction progresses according to plan, minimising the risk of overruns or delays.
During the construction phase, borrowers typically make interest-only payments on the amount drawn down from the loan. This helps borrowers to manage cash flow during the construction period, as borrowers are not required to make principal repayments until the property is completed.
Once construction is complete and the property has been inspected and approved, the loan may be converted to principal and interest repayments. Alternatively, depending on the borrower's preferences and financial situation, the loan may be retained as interest-only for a period of time.
Navigating the complexities of construction loans requires expertise and a thorough understanding of the construction process and financing options available. As your mortgage broker, we can guide you through the entire process, from selecting the right loan product to ensuring a smooth transition to principal and interest repayments upon completion.
Construction Loan Benefits
Construction loans offer a range of benefits to individuals and families, including;
Customised Financing
We'll work with you to find the financing solution that fits your needs, whether you're building a new home from scratch or renovating an existing property.
Flexible Repayment Options
We offer a range of repayment options to fit your budget and financial goals, including interest-only repayments during the construction phase.
Competitive Rates
Our construction loans offer competitive rates and terms, allowing you to save money on interest charges and reduce the overall cost of your project.
How it Works
We want to help you achieve your finance goals whether it is getting you into a new home or assisting with an investment property. Here's the process on how we get your home loan approved quickly.
Initial discovery call
Chat with us to discuss your specific financial goals and dreams.
Research, Planning and Comparison
We work hard to present to you the best solution, lender and interest rate based off our initial discovery call.
Submit your application
We will help you complete all the necessary paperwork and requirements with your chosen lender to get your application sorted.
Ongoing Support
We will monitor your application and keep in touch along the way. We work behind the scenes to make sure everything is as smooth for you as possible.
Frequently asked questions
Common questions about construction loans and progress payments, answered by our brokers.
How does a construction loan work?
A construction loan is a home loan specifically designed for building a new home or major renovation, where funds are drawn down in stages as construction progresses. You only pay interest on the amount drawn, not the full loan. Your broker manages the lender relationship and ensures each progress payment aligns with the build.
What are progress payments?
Progress payments are staged drawdowns of your construction loan, released as each phase of the build is completed, such as slab, frame, lock-up and fixing. The lender typically inspects the work before releasing each payment. Your broker coordinates with the builder and lender to keep the payment schedule on track.
How much deposit do I need for a construction loan?
Most lenders require a deposit of at least ten to twenty percent for a construction loan, depending on the lender and whether you are building or buying land plus construction. Some lenders accept equity in your land as the deposit. Your broker can confirm the deposit requirements of each construction lender on our panel.
What happens if my build runs over budget?
If your build runs over budget, you may need to cover the shortfall from your own funds, as lenders only lend up to the approved loan amount. Some lenders allow variations, subject to reassessment. Your broker can help you plan a contingency buffer and review the fixed-price building contract before construction begins.