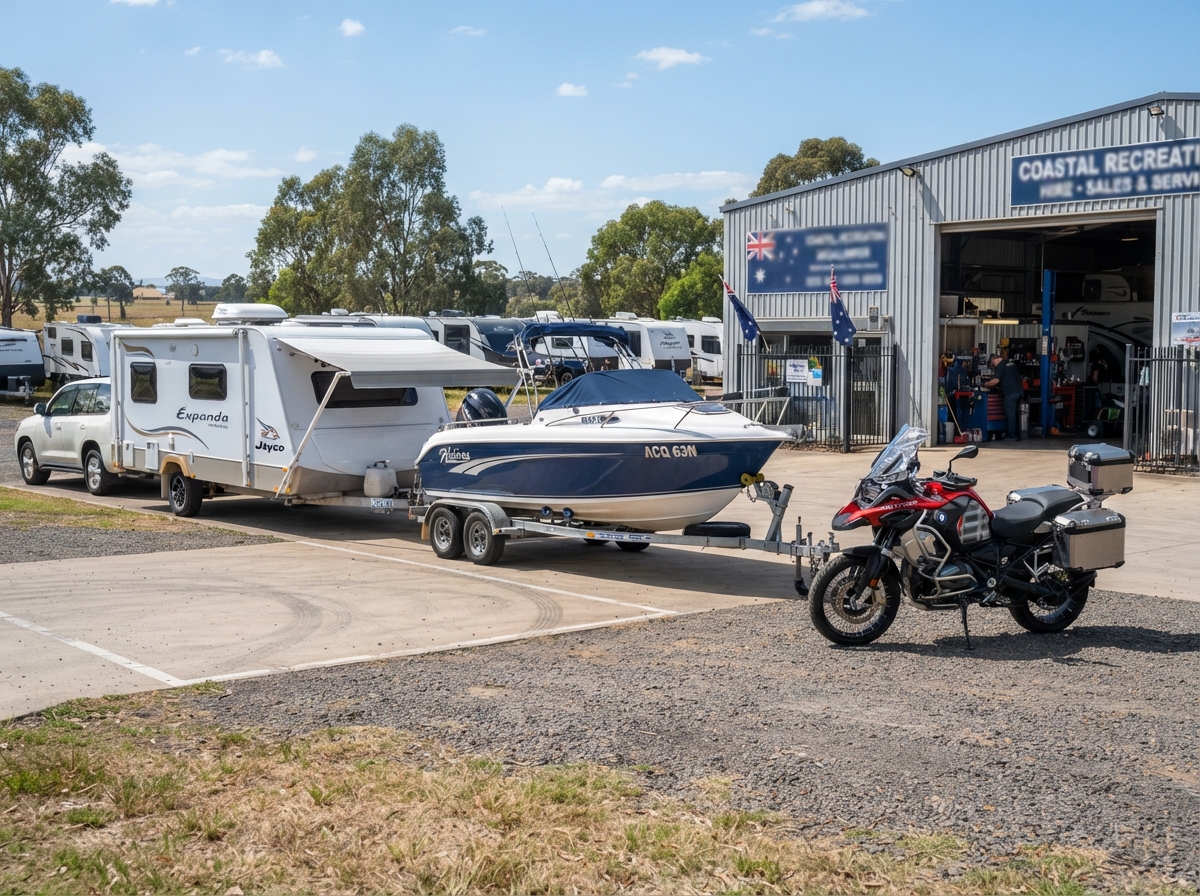
Finance for the assets that drive your business
Motorbikes, boats, caravans, plant and machinery. We compare 28+ lenders to find the right finance for your next asset purchase.
Motorbike, Boat, or Caravan Finance for your business
Asset and equipment finance is a commercial loan used to purchase business assets such as machinery, vehicles, boats or caravans, where the asset itself typically serves as security for the loan. When your business needs to invest in essential assets be it equipment upgrades or to help you grow, speak to Gateway Finance. Use our loan repayment calculator to estimate your asset finance repayments.
Limiting your loan options to just one bank or one lender is limiting your business growth and investment opportunities. Gateway Finance breaks those limitations by offering you more lenders, more options and more chances to reduce your financing costs.
We deliver highly competitive and workable funding offers for plant, machinery and business machinery acquisitions, both new and second-hand. Offers from a wide selection of banks and lenders with your choice of commercial finance products, flexible terms and conditions and our signature low interest rates.
We will support your business beyond just one loan. Moving forward, as a respected client we can work with you to revitalise your operation with cheaper, more affordable finance options across multiple areas.
Chattel mortgage, finance lease or rental: which asset finance structure suits you?
Each structure affects ownership, tax treatment and your balance sheet differently.
| Feature | Chattel Mortgage | Finance Lease | Operating Rental |
|---|---|---|---|
| Ownership | You own the asset from day one, lender holds a mortgage over it | Lender owns the asset, you use it for an agreed term | Lender owns the asset, you pay to use it with no purchase obligation |
| Tax treatment | May allow GST credits and depreciation claims | Lease payments may be tax-deductible as a business expense | Rental payments are typically fully deductible as an operating expense |
| GST | GST is charged on the purchase price, claimable on your BAS | GST is built into the monthly lease payments | GST is included in the rental payments |
| End of term | You keep the asset outright | Option to purchase the asset at the residual value | Return the asset, upgrade, or extend the rental term |
| Balance sheet | Asset and loan appear on your balance sheet | Asset and liability may appear depending on structure | Usually off-balance-sheet, no asset or liability recorded |
| Best suited to | Businesses wanting outright ownership and depreciation benefits | Businesses wanting use of the asset with a predictable residual | Businesses wanting flexibility and no long-term commitment |
Ownership
You own the asset from day one, lender holds a mortgage over it
Lender owns the asset, you use it for an agreed term
Lender owns the asset, you pay to use it with no purchase obligation
Tax treatment
May allow GST credits and depreciation claims
Lease payments may be tax-deductible as a business expense
Rental payments are typically fully deductible as an operating expense
GST
GST is charged on the purchase price, claimable on your BAS
GST is built into the monthly lease payments
GST is included in the rental payments
End of term
You keep the asset outright
Option to purchase the asset at the residual value
Return the asset, upgrade, or extend the rental term
Balance sheet
Asset and loan appear on your balance sheet
Asset and liability may appear depending on structure
Usually off-balance-sheet, no asset or liability recorded
Best suited to
Businesses wanting outright ownership and depreciation benefits
Businesses wanting use of the asset with a predictable residual
Businesses wanting flexibility and no long-term commitment
Your accountant or our brokers can help you match the structure to your cash flow and tax position.
Benefits of using a broker for asset & equipment loans
If your business is looking at expanding and needs new equipment, vehicles or essential assets, using a broker is your best choice for securing your loan.
Customised Financing
We'll work with you to find the financing solution that fits your needs, whether you're looking at a new fleet of trucks, a new tractor or upgrading your computers.
Flexible Repayment Options
We offer a range of repayment options to fit your budget and business financial goals.
Competitive Rates
Our asset loans offer competitive rates and terms, allowing you to save money on interest charges and reduce the overall cost of your project.
New & Second-Hand
We deliver funding offers for plant, machinery and business equipment acquisitions, both new and second-hand.
Trusted Lenders
With most banks and lending facilities available to us, we broaden your options to secure better finance deals.
Fast Turnaround
We work efficiently behind the scenes to get your asset finance approved and your equipment on site sooner.
How it Works
We want to help you achieve your finance needs and get your new asset sooner. Here's the process on how we get your loan approved quickly.
Initial discovery call
Chat with us to discuss your specific financial goals for the business.
Research, Planning & Comparison
We work hard to present to you the best solution, lender and interest rate based off our initial discovery call.
Submit your application
We will help you complete all the necessary paperwork and requirements with your chosen lender to get your application sorted.
Ongoing Support
We will monitor your application and keep in touch along the way. We work behind the scenes to make sure everything is as smooth for you as possible.
Frequently asked questions
Common questions about asset and equipment finance, answered by our brokers.
What is the difference between a chattel mortgage and a lease?
A chattel mortgage means you own the asset from day one, with the lender holding a mortgage over it, while a lease means the lender owns the asset and you use it for an agreed term. Chattel mortgages suit businesses wanting ownership and depreciation benefits, while leases suit those prioritising predictable monthly costs.
Can I finance second-hand equipment?
Yes, many lenders will finance second-hand equipment, provided it meets their age and condition requirements. The asset typically serves as security for the loan. A broker can identify which lenders accept older or used assets and negotiate terms that reflect the equipment's remaining useful life and resale value.
What assets can be financed?
A wide range of business assets can be financed, including trucks, trailers, machinery, plant equipment, tractors, forklifts, boats, caravans, motorbikes, computers and office fit-outs. If the asset has a clear title and identifiable value, most lenders will consider it. Your broker can confirm which lenders accept the specific asset type you need.
What are the tax implications of equipment finance?
Equipment finance may offer tax benefits including GST credits on the purchase price, depreciation claims on the asset and deductibility of interest or lease payments. The specific treatment depends on the finance structure and your business circumstances. Your accountant can confirm what applies, while your broker helps match the structure to your position.
Ready to finance your next asset?
Let's find the right finance solution for your motorbike, boat, caravan, or business equipment. No credit impact to get started.
Start the process