We were recently mentioned in a Domain article where we helped one of our wonderful clients achieve what other mortgage firms had said was impossible. We literally helped make a single income earner and her mother’s dream come true!
Buyer diary: How this single income earner and her retiree mother entered the property market
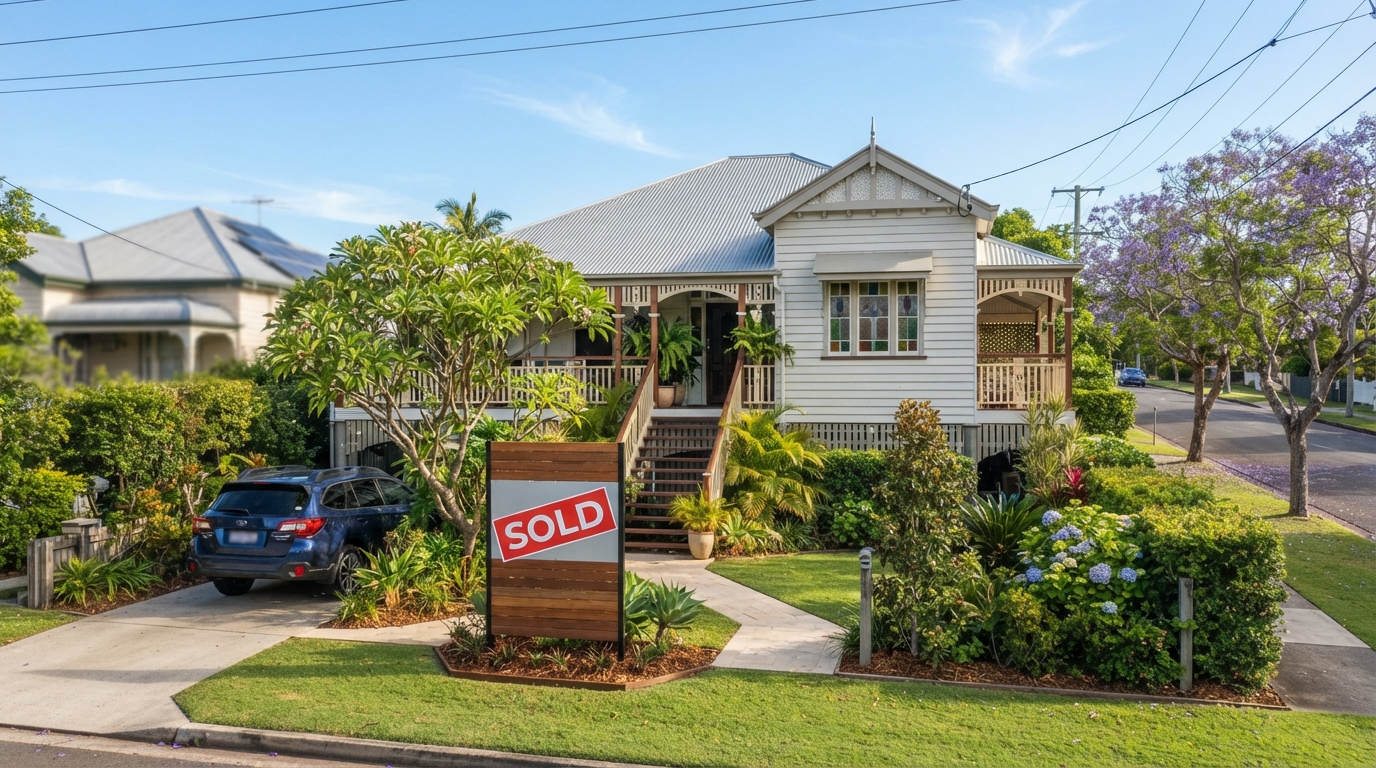
For my sister, Jasmine Skewes, and our mum, Patricia Skewes, buying a home was never just about property - it was about securing a future. As a single-income earner and a widowed single mother, respectively, home ownership once felt out of reach. However, with grit and determination, they made it happen, purchasing their own piece of the Australian dream.
Saving for a deposit took about two years. When the First Home Guarantee (FHBG) scheme expanded in July 2023 to include family members applying together, they were able to buy with just a 5 per cent deposit and no LMI.
"We started with a mortgage broker, but after one meeting, it was clear they weren't optimistic... A big shoutout to Mel Taylor of Gateway Finance who guided us through the process and secured our pre-approval!"
Borrowing Power
The amount you can borrow depends on income, expenses, credit history, and property value.
Interest Rates
Fixed or variable options determine the interest you'll pay on your principal balance.
Deposit & LMI
Deposits under 20% generally require LMI unless accessible via government guarantee schemes.
Loan Term
Standard loan terms in Australia span 25 to 30 years for manageable regular repayments.